Thinking About Value: Seven Situations to Recognize Before a Sale, Acquisition or Ownership Transition
A business valuation may be useful before a sale, acquisition, family transfer, tax reorganization or change in ownership. The right time to raise the question is while the information can still inform the decision.
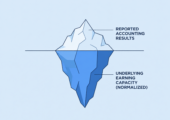
In Canada, an independent opinion of value concerns a specific subject—a business, its shares or an ownership interest—as of a particular date and within a defined framework. Its relevance and scope depend on the decision to be made and the intended use of the work. 6 — CBV Institute
For small and medium-sized business owners and their advisors—including tax specialists, CPAs, business lawyers and financial partners—the challenge is to recognize when a clearer understanding of value can help.
Make it a habit to ask about value before committing to a decision.
1. Planning retirement and the sale of your business
“I would like to retire in a few years.”
Establishing the value of your business early helps you assess whether your retirement plans are realistic and prepare for what comes next. This assessment forms part of succession planning, alongside your financial, tax and legal advisors. 1 — BDC
- Key takeaway: The estimated value of your business is not the net amount you will receive. Taxes, transaction costs and payment terms also need to be considered.
- Key action: Identify the amount your retirement plan relies on and confirm what it represents: the value of the business, the anticipated sale price or the expected net proceeds.
2. Assessing an offer to buy your business
“A competitor wants to buy my business.”
Before accepting or rejecting an offer, it is important to understand exactly what it covers: shares or assets, real estate, cash, debt, working capital and payment terms.
- Key takeaway: An independent opinion of value provides a reference point for assessing the offer and informing negotiations. The estimated value and the proposed price may differ. 2 — BDC
- Key action: Check whether the offer and your own estimate cover the same assets or ownership interests, as of the same date and under comparable assumptions.
3. Planning a family or intergenerational transfer
“My daughter wants to take over the business.”
Transferring a business within a family brings together emotional, financial and fairness considerations. An independent opinion of value can facilitate discussion and help reduce misunderstandings.
- Key takeaway: The economic value of the business and the successor’s ability to finance the acquisition are separate considerations. Both need to be examined when planning the transfer.
- Key action: Clarify which shares will be transferred, at what stage and according to the family’s timeline.
4. Reorganizing share ownership or planning an estate freeze
“We want to restructure share ownership before the transfer.”
A tax reorganization or estate freeze may require the value of the relevant property or shares to be established. In certain tax reorganizations, fair market value must be determined and appropriately documented. 3 — CRA
- Key takeaway: A price adjustment clause does not replace a genuine effort to establish that value at the outset. Whether the Canada Revenue Agency recognizes the clause depends on specific conditions. 4 — CRA
- Key action: Confirm with your tax advisor the planned transaction, the property or shares involved, and the date as of which value must be determined.
5. Arranging a shareholder buyout or employee ownership
“My business partner wants to leave,” or “We want to offer shares to a key employee.”
A business partner’s departure and an employee becoming a shareholder both raise questions about value and transfer terms. A shareholder agreement may govern these transactions. 5 — Corporations Canada
- Key takeaway: The terms of the shareholder agreement and the size of the interest, whether a minority or majority interest, can affect the value of the shares.
- Key action: Review the shareholder agreement before taking further steps to identify any prescribed valuation formula or process.
6. Preparing financing for an acquisition or ownership transition
“Our successor is ready, but how will they finance the acquisition?”
An acquisition must be financially viable for the buyer while meeting the requirements of financial institutions.
- Key takeaway: The value of the business, the negotiated price and the buyer’s ability to service debt are three distinct but related concepts.
- Key action: Use the valuation as a reference point for discussions about price and transaction structure, while confirming the lender’s financing requirements.
7. Updating a valuation after a significant change
“We already have a valuation, but circumstances have changed.”
A valuation relates to a particular date and specific assumptions. Before relying on it for a new decision, consider whether the circumstances have changed.
- Key takeaway: Rapid growth, the loss or addition of a major customer, or the departure of a key person can alter the business’s prospects and risks, and may therefore affect its value.
- Key action: Have the assumptions underlying your most recent valuation reviewed for relevance before relying on it for a new transaction.
What should you clarify before a business valuation?
The first step is to define the decision the valuation will help inform. These questions help establish the scope of the engagement. 6 — CBV Institute
- The decision: Are you planning a succession, assessing an offer, structuring a transaction or arranging a buyout?
- The subject: Are you valuing specific assets, all the shares or a particular ownership interest?
- The date: As of what date does value need to be determined?
- The framework: What definition of value and which tax or contractual provisions apply?
- The intended use: Who will use the work, and what scope will be appropriate?
For referring professionals, this information provides a useful starting point for a discussion with the valuator, even when the client’s plans are still taking shape.
Frequently asked questions about business valuation in Canada
How is a small or medium-sized business valued?
Depending on the business and the subject of the engagement, the valuator may use methods based on earnings or cash flow, market data, or assets. The choice depends in part on the business’s circumstances and the information available. 2 — BDC
Does an offer to buy a business constitute an opinion of value?
An offer reflects what a buyer proposes to pay, based on their terms and objectives. An independent opinion of value follows a defined framework. Comparing the two requires an understanding of their assumptions and what is included in the transaction. 2 — BDC
What information should you prepare before consulting a valuator?
Start with the decision to be made, the subject to be valued, the relevant valuation date and the timeline. Financial statements, available forecasts and transaction documents will then help define the work required. 6 — CBV Institute
For a closer look at the distinction, read our article on fair market value and selling price.
Prepare for the next step
Once the purpose is clear, use our business valuation checklist of 12 documents to prepare. To better understand the financial information involved, read about normalized EBITDA and earnings adjustments.
Discuss your situation with a business valuator
SME Business Appraisers works with business owners and their advisors, primarily in Quebec and Ontario.
Are you preparing for a sale, succession or change in ownership? Are you advising a client in one of these situations? Tell us about the decision to be made, the parties involved and the anticipated timeline. Together, we can consider whether an independent opinion of value would be useful and what scope of work may be appropriate.
A clear, rigorous and independent opinion of value.
Sources
- BDC — Succession planning: Who will take over the family business?
- BDC — How to sell your business
- Canada Revenue Agency — IC76-19R3: Transfer of Property to a Corporation Under Section 85, paragraph 6
- Canada Revenue Agency — Income Tax Folio S4-F3-C1: Price Adjustment Clauses, paragraph 1.5
- Corporations Canada — Share structure and shareholders
- CBV Institute — Practice Standard No. 120: Valuation Conclusions and Valuation Reports — Scope of Work Standards, effective January 1, 2026